Loft Conversion Insurance
Specialist trade cover for loft conversion building projects from £3.27 a month.*
- Public Liability for loft conversion
- Tools and equipment cover
- Professional Indemnity
- Fast online quotes
- Join over 180,000 customers**
From £2.89* a month
What does loft conversion insurance cover?
Loft conversion insurance is designed for sole traders, contractors and small building businesses carrying out conversion projects in customers’ homes.
Public Liability Insurance is usually the starting point, helping protect your business if someone is injured or you accidentally damage third-party property while carrying out insured work. This can be particularly important on loft projects, where you may be working throughout an occupied property, moving materials through the home and carrying out building work above existing living spaces.
You can then add cover to reflect the type and size of projects you take on. This can include protection for your own tools and equipment, hired plant and machinery, and additional cover for insured tools kept securely in a vehicle.
Contractors Works cover can provide protection for eligible building work and materials while the conversion is underway, helping to safeguard the investment you have already made in labour and materials before the project is handed over.
Employers’ Liability Insurance can also be included if you employ staff, while Professional Indemnity Insurance may be relevant where your business provides professional designs, specifications, calculations or other technical advice as part of the conversion.
Whether you work independently on smaller loft projects or manage a team across more substantial conversions, you can build your insurance around the work your business undertakes.
Make sure you have the correct insurance for your trade and be sure to check if any exclusions are relevant to what you have planned in policy documentation.

Public Liability

Professional Indemnity
Employers' Liability
Contractors Works
Plant & Tools
Public Liability for loft conversions
- Cover of up to £5 million is available.
- Protects you against claims from third parties, such as customers or members of the public, who are injured or whose property is damaged because of your work.
- Does not cover damage to third-party property that forms part of the contract or construction site you are working on.
Public Liability Insurance excludes damage to property that forms part of the construction project or worksite.
For example, if you are working on a property owned by someone else and accidentally damage part of the project itself, this would not be covered under Public Liability Insurance.
This protection can be added through Contract Works cover.
Professional Indemnity
- Cover up to £500,000 is available.
- Protects you if a customer claims they have suffered a financial loss because of a professional mistake, such as incorrect advice, an error in a design or specification, or important information being missed.
- Covers claims arising from negligent acts, errors or omissions by you or your employees while providing professional services.
- Does not typically cover poor workmanship, faulty materials or the cost of correcting defective work. See full policy terms.
Employers’ Liability
- Cover of up to £10 million is available.
- Covers claims if an employee, labourer, apprentice or other member of staff is injured or dies because of the employer’s negligence.
- If they or their representative seek compensation, the insurer can handle the cost of the claim, provided terms have been complied with.
- Employers’ Liability Insurance is a legal requirement if you employ any staff members.
Contractors Works
- Cover of up to £250,000 is available.
- Covers loss of or damage to permanent and temporary building works you are responsible for.
- Includes materials being used as part of the job.
Hired plant & tools cover
- Cover of up to £50,000 is available.
- Covers loss of or damage to tools, equipment, temporary buildings, caravans or similar items you hire for your contract work.
- Also covers your legal liability for ongoing hire charges following damage to hired property.
Owned plant & tools cover
- Cover of up to £75,000 is available.
- Covers tools, equipment, temporary buildings, caravans or similar items you own and use on-site for your contract work.
Tools left in a vehicle
- Available as an extension to Owned plant and tools cover only.
- Covers your portable tools, including power tools and business equipment, when locked in an unattended vehicle away from the worksite.
Employees tools & personal effects
- Provides cover of up to £1000.
- Covers tools and personal belongings owned by your employees while they are working on-site.
- Also covers items belonging to people you are responsible for under a joint working agreement.
- This is not available as standalone cover. It must be included with Contract Works, Owned Plant and Tools or Hired Plant and Tools cover.
Financial Loss
- Provides up to £50,000 of cover, for accidental financial loss to another party that you are liable for.
- Covers you if a customer suffers a financial loss that is not caused by injury or property damage and you are legally liable.
- This does not include cover for financial losses relating to non-completion or late completion of works you are undertaking.
There are some situations where protection will not apply. This can include:
- Bona fide subcontractors who are expected to hold their own appropriate insurance.
- Any work undertaken over 15m from the surrounding ground level.
- Poor workmanship or the cost of correcting your own work.
- Work you are not qualified or legally permitted to carry out, where specific qualifications, registrations or regulatory requirements apply.
For information on exclusions in your cover please refer to policy documentation.
Why is insurance important for loft conversion contractors?
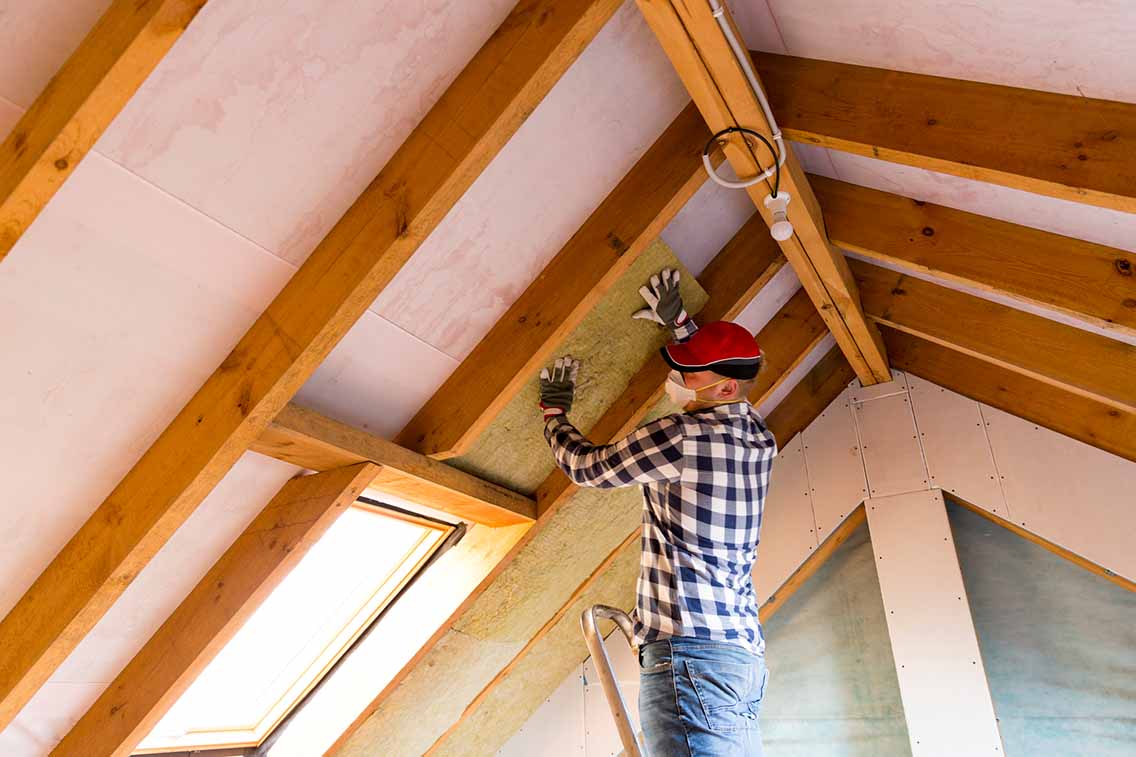
A loft conversion can involve much more than working in a single room. Projects can include structural alterations, new floors and walls, staircases, roofing work, insulation, windows and the movement of building materials through an existing home.
That combination creates a range of potential risks. An accident could damage another part of the property, someone could be injured around the works, valuable tools could be stolen or materials and completed sections of the conversion could be damaged before the project is finished.
Insurance can help protect your business against the financial consequences of these unexpected events, while also providing cover for some of the equipment and project costs you have invested in.
For contractors working on larger projects, suitable insurance may also be requested by customers, architects, principal contractors or other parties involved in the work.
Protection from claims if a clients' property is damaged.
Loft conversions often take place directly above occupied areas of a customer’s home.
Building materials, tools and structural alterations can all create the possibility of accidental damage extending beyond the section you are working on.
If your business is held responsible, public liability insurance can help with eligible compensation and legal costs arising from the claim.
Public liability would not normally cover the cost of putting right defective workmanship or damage to the part of the property that forms part of your contracted work, so it is important to understand how this works alongside Contractors Works cover.
An employee is injured while working on the project.
Loft conversion work can involve lifting and carrying materials, working at height, using power tools and operating in confined or awkward spaces.
If an employee, apprentice or temporary worker suffers an injury while carrying out work for your business and makes a claim, Employers’ Liability Insurance can help cover the associated costs.
For most businesses employing staff, employers’ liability insurance is also a legal requirement.
Your tools or building equipment are damaged or stolen.
Loft conversion contractors can depend on a broad range of builders’ tools, from drills, saws and nail guns to measuring equipment, hand tools and other portable machinery.
Losing essential equipment can do more than create a replacement cost. It may also delay work and make it difficult to keep the project on schedule.
Tools and equipment cover can protect eligible insured items against specified loss or damage. You can also select cover for hired equipment and, where included, protection for insured tools kept securely in your vehicle.
Building work or materials are damaged before completion.
Loft conversions often run over several weeks and can involve significant amounts of timber, insulation, plasterboard, roofing materials, windows and other building components.
During that time, both materials and completed sections of the conversion may remain exposed to unexpected damage.
Contractors Works cover can protect eligible work in progress and materials associated with the insured contract, helping reduce the financial impact if part of the project has to be replaced or completed again before handover.
You provide designs, specifications or structural advice.
Some loft conversion businesses provide more than the physical building work. You may also advise customers on the project, produce specifications or take responsibility for aspects of the design.
Where professional services form part of what you provide, Professional Indemnity Insurance can offer protection if a client alleges that an error, omission or negligent piece of professional advice has caused them a financial loss.
It does not usually cover defective workmanship or the cost of simply correcting your own construction work, so it provides a different type of protection from Public Liability and Contractors Works insurance.
Our experts explain why...
“Loft conversions can be significant projects, combining structural building work with the added challenge of working in and around an existing home. Even experienced contractors can encounter unexpected problems, whether that’s accidental damage elsewhere in the property, an injury on site, stolen equipment or damage to work before the conversion is finished.
The right insurance gives loft conversion contractors the flexibility to protect more than just their liability. From essential tools and equipment to work in progress and professional services, cover can be selected around the way you run your business and the projects you take on.”
Chris Trotman – Head of Sales & Underwriting – Protectivity
How much does loft conversion insurance cost?
Loft conversion insurance starts from just £3.27* a month.
The cost of insurance for a loft conversion business will depend on the scale of your operations, the type of work you undertake and the protection you choose.
A sole trader completing smaller residential conversions may have different requirements from a contractor employing a team and managing several larger projects at the same time.
Factors such as your turnover, number of employees, the nature and value of the contracts you undertake and the level of Public Liability Insurance selected can all influence your premium.
The optional covers you add will also affect the price. This could include the value of owned tools and equipment you want to insure, hired plant, the level of Contractors Works protection required and whether you need Professional Indemnity Insurance for design, specification or advisory work.
Selecting cover around the size and scope of your loft conversion business helps you put protection in place that reflects the projects you actually deliver.
Prices from
£3.27* a month
Explainer Quote
Policy cost
£3.27* a month
Policy type
Loft Conversion / General Builders
Duration
Annual
Turnover
Up to £150,000
Public Liability
Up to £1,000,000
This example is based on a real quote from our website on 21/09/2026. If your circumstances and cover needs differ, your quote may be more or less expensive than the above example. The quote you receive will reflect the information you share about your event. The quoted price may vary from those displayed here.
Have a question?
For further information on your policy, renewals, making a claim and contacting us, you’ll find an extensive list of FAQs on our Help & Support page.
Why choose Protectivity for your loft conversion insurance policy?
Let the reviews of over 3,500 customers explain why you should choose us.¹
Trusted by over 180,000 customers.
Experienced insurance providers for over 30 years.
Over 3,500 highly rated reviews.
Proof of our excellent customer service.

Experienced Claims Handling
A smooth and efficient claims process.

UK Based Customer Support
On average we answer your phone calls in under 2 minutes
Discover more from Protectivity
This page content has been created for general information and should not be taken as advice.
*Prices quoted refer to a quote raised from our website 21/09/2026. Prices will differ depending on requirements. Make sure you have the correct level of cover for what you need. For the most accurate pricing, please get a quote and for full details on what is covered refer to our policy documentation with your quote.
** Based on Protectivity sales data from 2007 to present
¹Based on live Feefo data