Table of contents
Table of contents
Contributors
Tegan joined the marketing team in 2023 and works as a Marketing Executive, supporting a wide range of activity a...
You have done the work, made the sale or delivered the service. Now you need to get paid.
For a small business, getting paid and making payments should be straightforward for both you and your customer. But with so many ways to accept money – from cash and bank transfers to card payments, online checkouts and payment links – it can be difficult to know which option is right for your business.
The answer does not necessarily involve choosing the newest or most sophisticated payment system. Instead, it comes down to understanding how your customers buy from you, where they expect to pay and what makes the process easiest to manage afterwards.
A tradesperson might send an invoice after completing a job, while a market seller could take contactless payments using a mobile card reader. An online retailer needs a checkout that allows customers to pay as part of their purchase, while a consultant might take a deposit before starting a project and invoice the remaining balance later.
Payment habits in the UK also continue to change. UK Finance reported that 49.7 billion payments were made in the UK during 2025, with card payments accounting for 64% of all payments. Contactless payments reached 19.2 billion, representing 39% of all payments, while cash accounted for 8%.
This does not mean every small business needs to become completely cashless or offer every possible payment option. It means there is value in choosing payment methods that match the way your customers already want to buy.
So, what payment methods can your small business use, what do they cost and how can you make it easier to get paid?
What payment methods can small businesses use?
Small businesses can accept payments in several different ways, and the most suitable combination will depend on the type of business you run.
| Payment method | Common fit |
| Bank transfer | Trades, freelancers and invoiced services |
| Card/contactless | Shops, salons, events and in-person services |
| Mobile card reader | Markets and mobile businesses |
| Online checkout | Ecommerce |
| Payment link | Remote services and invoices |
| Recurring payment | Regular customers and subscriptions |
Cash
Cash remains an option for businesses that sell face-to-face. It can be particularly useful at markets, events or in situations where customers may not want to pay digitally.
However, accepting cash also means thinking about how you will record transactions, store money securely and get cash into your business account. It can also create more administration when you are trying to reconcile your sales with your bank records.
Cash does not necessarily need to disappear from your payment options, but consider whether it is genuinely useful for your customers and business.
Bank transfer
Bank transfer can be a simple way for freelancers, contractors, tradespeople and other businesses that invoice customers to receive payment.
You provide your bank details, and the customer transfers the money from their bank account. Faster Payments can make this particularly convenient, with payments generally moving quickly between participating banks.
For a business sending invoices, bank transfer has another advantage: it does not necessarily require specialist payment hardware. However, you need to make sure your payment instructions are clear and that you have a reliable process for matching incoming payments to the correct customer or invoice.
Card and contactless payments
Card payments are now an important part of everyday spending in the UK. Debit cards remained the country’s most-used payment method in 2025, while contactless payments reached 19.2 billion.
For a business selling face-to-face, accepting cards can therefore remove a potential barrier at the point of purchase.
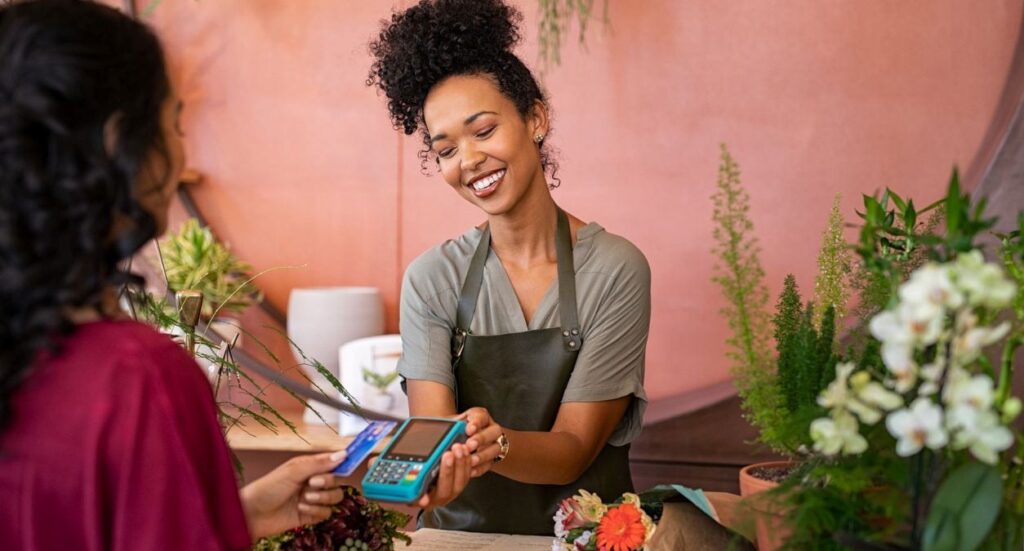
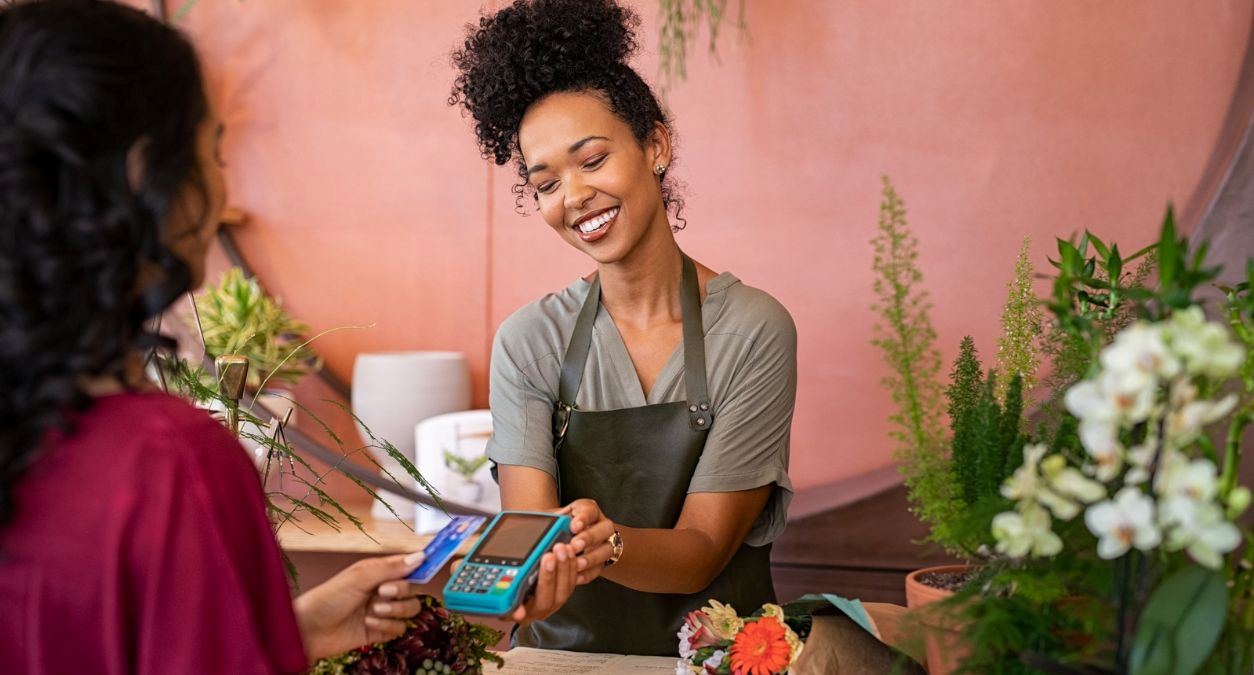
A salon, café, shop, event business or service provider might use a card terminal or reader to take payment immediately. Customers can often use a physical card or mobile wallet, depending on the equipment and payment provider.
The main consideration is cost. Card payments normally involve some form of transaction fee, and there may also be costs for hardware or a subscription, depending on the system you choose.
Mobile card readers
Mobile card readers can be particularly useful if your business does not operate from one fixed location.
A market trader, mobile hairdresser, personal trainer, tradesperson or instructor, for example, could take card or contactless payment at a customer’s home, at an event or while working outdoors.
This can be useful when you want customers to pay immediately rather than sending an invoice after the job. You may still want bank transfer or another option available for larger payments.
Online checkout
If you sell products or services through a website, an online checkout allows customers to pay as part of the buying journey.
The payment process should be easy to find and straightforward to complete. If customers have to navigate several pages, create unnecessary accounts or search for payment information, they may abandon the purchase.
Online spending is a significant part of how consumers pay. The Office for National Statistics found that online spending accounted for 50.5% of total UK card spending in September 2025, compared with 43.7% in September 2019.
That does not mean every business needs an ecommerce website. But if your customers buy online, your payment process needs to work as well as the rest of the buying experience.
Payment links
Payment links can be useful when you sell remotely but do not need a full ecommerce checkout.
For example, a consultant could finish a project and send a customer a payment link alongside their invoice. A tradesperson might send a link after completing a job. A small service business could use one when taking a deposit.
The benefit is convenience: the customer has a clear route to payment without necessarily needing to manually enter bank details.
Recurring payments
If customers pay you regularly, recurring payments may be worth considering.
This could apply to subscriptions, memberships, ongoing services or regular maintenance arrangements. Depending on the business model, you may use Direct Debit or recurring card payments.
The important consideration is whether recurring payments genuinely suit your relationship with the customer. If payment amounts or dates vary significantly, another arrangement may be simpler.
Which payment method suits your business?
The right payment system follows the way you sell.
Rather than starting with a particular provider or piece of technology, start with your customer journey. Ask how customers find you, how they buy, when they expect to pay and what happens after they have made the payment.
Face-to-face shops and salons
If customers visit you in person, card and contactless payments are likely to be useful.
Imagine a customer visiting a hair salon. They have received their service and want to pay before leaving. A card reader allows the transaction to happen immediately, without requiring the customer to find cash or remember to make a bank transfer later.
The same principle applies to many other face-to-face businesses. The easier payment is at the point of sale, the less likely you are to create an unnecessary follow-up.
Cash could still be offered as an alternative if it is appropriate for your customers.
Mobile tradespeople and instructors
For businesses that travel to customers, flexibility can be more important.
A tradesperson might normally invoice customers for larger jobs but want to accept a card payment or bank transfer for smaller jobs. A driving instructor, personal trainer or tutor could also benefit from having a straightforward way to accept payment away from a traditional business premises.
A mobile card reader can provide one option, while a payment link or bank transfer can provide another.
The important thing is not to overcomplicate the process. If one payment method works well for most customers, add a second option only where it solves a genuine problem.
Ecommerce sellers
For online businesses, payment forms part of the customer experience.
Customers need to know what they are buying, what it costs and how they can pay. A checkout that is confusing or difficult to use can create friction at exactly the point when someone is ready to purchase.
ONS data shows that the proportion of UK card spending taking place online has increased since 2019, underlining the importance of digital payment journeys for businesses selling online.
For an ecommerce business, therefore, choosing a payment system should involve considering the complete checkout experience rather than simply looking for the lowest transaction fee.
Freelancers and B2B businesses
For freelancers and businesses that invoice, bank transfer may be the obvious starting point.
However, there can be value in offering another way to pay. A payment link alongside bank transfer, for example, gives customers a choice without requiring you to maintain a complicated range of systems.
This can be particularly useful when customers are busy or paying remotely. The easier it is for them to complete the payment, the less opportunity there is for an invoice to sit unanswered.
How much do payment systems cost?
Payment systems can involve several different costs, so it is important to look beyond the headline transaction fee.
Depending on the system, you may encounter:
- a percentage charged on each transaction;
- a fixed fee per payment;
- a monthly subscription;
- hardware or card-reader costs; and
- additional ecommerce or software fees.
The cheapest option will depend on how your business actually uses the system.
For example, a business taking 20 payments a month may have very different priorities from one taking 2,000. Likewise, a business taking high-value payments may be more affected by a percentage fee than one making lots of small transactions.
Before choosing a system, estimate your likely payment volume and average transaction value. Then consider the total cost rather than focusing on one fee.
It is also worth considering administration.
Suppose one payment system costs slightly more per transaction but automatically feeds information into the software you already use. If that saves you hours of manual administration each month, the additional cost could potentially be worthwhile.
Look at:
- Transaction volume: How many payments do you expect to take?
- Average transaction value: Are customers generally paying £20, £200 or £2,000?
- Fixed costs: Will you have a monthly subscription or hardware expense regardless of how much you sell?
- Administration: How easy will it be to reconcile payments with your invoices, sales and accounts?
Provider fees and features can change, so check current pricing directly before committing to a particular system.
How can you make it easier to get paid?
Choosing a payment system is only one part of getting paid promptly.
Your wider payment process can make a significant difference too.
Agree payment terms upfront
Make sure customers know when payment is due before the work starts or the sale is completed.
For larger projects, consider whether a deposit or staged payment arrangement makes sense. For example, a contractor might agree a deposit before purchasing materials and a final payment when the work is completed.
Clear expectations can reduce confusion later.
Invoice promptly
If your business relies on invoices, avoid unnecessary delays between completing the work and sending the invoice.
An invoice should make it clear what the customer is paying for, how much they owe, when payment is due and how they can pay.
The sooner the customer receives that information, the sooner they can act on it.
Make payment instructions obvious
Do not make customers search through an email or attachment to work out how to pay.
If you accept bank transfer, make the relevant details easy to find. If you accept payment through a link, make the link clear and distinguishable from other information.
The objective is simple: when a customer is ready to pay, they should know what to do next.
Offer useful choices
You do not need to offer every possible payment method.
Instead, think about the most common situations your customers face. A tradesperson might offer bank transfer and card payment. A freelancer might accept bank transfer but also provide a payment link. An ecommerce business might offer several digital payment options at checkout.
The right combination is the one that removes friction without creating unnecessary cost or administration for you.
Use reminders where appropriate
Sometimes customers simply forget.
Having a consistent process for following up overdue invoices can help you avoid relying on memory. A polite reminder shortly before or after the due date may be enough to prompt payment.
If late payments are a recurring issue, it may be worth reviewing your payment terms and the process customers go through from receiving an invoice to making payment.
A delay is not always caused by an unwilling customer. Sometimes the payment process itself is inconvenient, unclear or difficult to complete.
Do not forget what happens after payment
Getting the money into your account is not the end of the payment journey.
You also need to know what the payment relates to and make sure your records are accurate.
For example, if you receive five bank transfers in one day, can you quickly identify which invoices they relate to? If you take card payments throughout the week, can you reconcile those transactions with your sales records?
Good record keeping becomes increasingly important as your business grows.
Government research shows that digital tools are already widely used by small businesses. In 2025, 55% of businesses with no employees used technology or web-based software to sell to customers or manage the business, while 74% of SME employers did so. Among SME employers using technology, accountancy software was the most common tool, followed by payroll software and electronic invoicing.
For a small business, connecting payment information with invoicing or accounting software where appropriate can reduce some of the administrative work.
Keeping records up to date can also help you understand your cash position and identify customers who may need a reminder.
Have a backup when digital payments go wrong
Digital payments can make life easier, but no system is completely immune from problems.
A card reader could fail. Your internet connection might drop. A payment platform could experience an outage. A customer could arrive without the payment method you normally use.
That does not mean you need to maintain a long list of alternative systems. Instead, think about the most realistic problems your business could encounter.
Ask yourself: If my usual payment method stopped working today, could my customers still pay me?
For a mobile business, that might mean being able to accept a bank transfer if a card reader cannot connect.
For a business that normally accepts online payments, you might have a clear process for handling an order if the usual checkout is temporarily unavailable.
For an invoiced business, your backup could simply be having clear bank details available.
The right solution depends on your business. What matters is having considered the question before an interruption happens.
Make getting paid part of a good business process
Getting paid is one of the most important parts of running a business, but choosing a payment system does not need to be complicated.
Start with your customer.
How do they buy from you? Do they visit you in person, book your services remotely, buy through your website or receive an invoice? When do they expect to pay? What payment method is likely to be most convenient for them? And once the money arrives, how easily can you match it to the relevant sale or invoice?
The answers should guide your choice.
A tradesperson may find that bank transfer combined with a payment link or card reader works well. A shop or salon may prioritise card and contactless payments. An ecommerce business needs a reliable online checkout, while a freelancer may simply need an efficient invoicing and bank-transfer process.
You do not necessarily need to offer every payment method available. In many cases, one or two well-chosen options will be more useful than a complicated system that creates unnecessary costs and administration.
Most importantly, make getting paid part of your wider business process. Agree payment terms before the sale, invoice promptly where necessary, make payment instructions clear, keep accurate records and follow up consistently when payments are late.
A reliable payment process can help keep money moving through your business and make day-to-day administration easier. It is one part of building a resilient business, alongside having suitable protection for the wider risks that can come with your work.
Get Small Business Insurance from Protectivity
*Disclaimer – This blog has been created as general information and should not be taken as advice. Make sure you have the correct level of insurance for your requirements and always review policy documentation. Information is factually accurate at the time of publishing but may have become out of date.
Last updated by