Theatre & Performing Arts Club Insurance
Specialist theatre & performing arts club insurance from £3.62 per month*.
- Public Liability up to £10 million
- Join 180,000 customers**
- Flexible Payment Plans – 0% APR
Save 10% Online
From £3.62* a month
What does theatre & performing arts club insurance cover?
Theatre & Performing Arts club insurance is tailored to cover sports clubs of all sizes, along with their members and assets, from various risks. You can customise the cover to suit your specific needs.
Our Theatre & Performing Arts policy includes essential protections like public liability and professional indemnity, along with equipment cover. You also have the option to add employers’ liability and personal accident insurance if required.
Make sure you have the correct insurance for your event and be sure to check if any exclusions are relevant to what you have planned in policy documentation.

Public Liability

Professional Indemnity
Equipment
Employers’ Liability
Personal Accident
Public Liability
- From £2 million to £10 million of cover.
- Protection from claims by a third-party who sustains injuries or has their property damaged as a result of your actions.
Professional Indemnity
- Up to £1 million.
- This covers the club’s legal liability to pay damages in the event of a breach of professional duty due to a negligent act, error or omission by the club or an employee.
Employers’ Liability
- £10 million worth of cover.
- Protection from claims against employee incidents if someone suffers a work-related injury and brings a claim against you.
Sports Equipment
- Up to £30,000 of equipment cover.
- Protecting equipment you need for your club from loss, damage and theft.
Personal Accident Cover
- Protection for the person(s) insured, should they suffer a bodily injury caused by an accident at the business or club insured.
- A selection of incidents can be claimed for under this benefit including accidental death, permanent total disablement and temporary total disablement.
Directors & Officers Cover
- Financial protection for directors and association officials in respect of their personal liability whilst working for the club or association.
- Coaching any activity without the relevant qualification.
- Equipment that’s left in plain sight or in an unlocked vehicle, and where there’s no sign of forced entry or damage.
- The organisation of any disco or live music event open to the public. (‘Live music’ does not include choirs & orchestras).
- Any use of pyrotechnics.
For further information on exclusions in your cover please refer to policy documentation.
Public and Products Liability
- From £1 million to £10 million of cover.
- Protection from claims by a third-party who sustains injuries or has their property damaged as a result of your actions or products provided to customers, that have left your custody.
Professional Indemnity
- Up to £1 million of cover.
- Protection from claims by a third-party who sustains injuries or has their property damaged as a result of advice and instruction that you and your staff provide.
Employers’ Liability
- £10 million worth of cover.
- Protection from claims against employee incidents if someone suffers a work-related injury and brings a claim against you.
Building & Contents
- Cover for your Buildings, Gym Equipment, Computer Hardware, General Contents, Portable Sports / Activity related equipment and many more.
- All risks insurance cover designed to protect your business premise, bricks and mortar and everything you store in it.
Business Interruption
- Cover can be for your businesses gross revenue, gross profit or gross rentals from other parties you rent out property too.
- Specialist cover for interruption to your business caused by an insurable claim within the Material Damage cover and a few other extensions.
Legal Expenses
- Cover for up to £100,000 of cover for Legal Defence, Tax Protection and access to specialist help-lines.
- Includes cover for employment, property and contract disputes, as well as health and safety appeals, jury service, court attendance and licence protection.
- Contracted instructors will need to have their own insurance.
- General policy exclusions for Asbestos, Cyber, Punitive Damages, Radioactive Contamination, Terrorism and War.
For further information on exclusions in your cover please refer to policy documentation.
Why do you need theatre & performing arts club insurance?
Running a theatre & performing arts club requires a lot of dedication. Ensuring the safety of your members and keeping the club’s finances stable are key parts of the job. Even with the best intentions, unexpected incidents can happen, often beyond your control.
Theatre & performing arts insurance provides essential protection against potential claims. With this cover, you can focus on running your club smoothly, fulfil safety responsibilities for your members and the public, and safeguard the club from significant financial risks.
Here are a few examples to demonstrate the importance of theatre & performing arts club insurance:
Cover against claims from public injury.
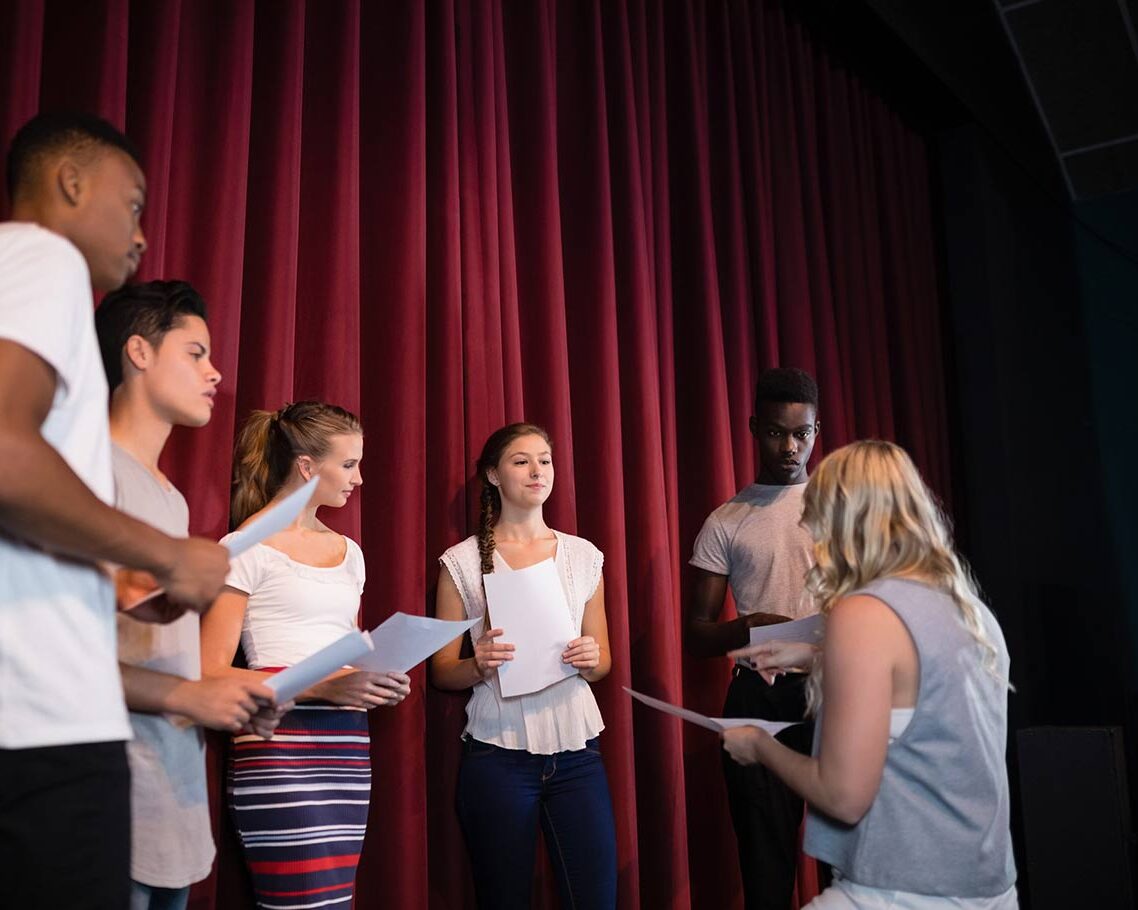
Theatre clubs often host events and engage with people in public spaces. In the event that a member of the public is injured or their property is damaged during a club activity, public liability insurance can provide protection against potential legal claims.
A volunteer suffers a workplace accident.
One of your volunteers gets injured while setting up for an event and requires medical leave from work. If your club doesn’t have appropriate insurance, you might face legal action and compensation claims.
Employers’ Liability Insurance covers claims related to work-related injuries or illnesses among your staff and volunteers. This not only ensures legal compliance but also demonstrates your club’s commitment to supporting and protecting those who contribute to its success.
Avoid losses from expensive equipment.
After a major event, you discover that several pieces of expensive equipment have been stolen or damaged. Replacing these items out-of-pocket would strain your club’s budget.
Equipment cover can avoid costly replacements in case your equipment is damaged or stolen.
You are forced to close temporarily.
Imagine your club’s main building suffers extensive damage due to a fire, forcing you to halt all activities and rebuild. The costs and loss of income during this period could be devastating.
Should your club have to close for a period of time having business interruption cover can protect you from the financial losses associated with this closure.
Our experts explain why...
“We have adapted our product offering to recognise the changing demands of sports clubs, so we can make sure, whatever you are offering to your customers or members, we can provide you financial protection. Our insurance offering doesn’t just cover your Public Liability concerns but also those that might come from suggested negligent advice and tuition, through our Professional Indemnity extension, which we offer at no additional charge.”
Chris Trotman, Protectivity Underwriting Manager
How much does theatre club insurance cost?
The cost of Theatre & Performing arts club insurance can vary depending on the level of cover you need. For example, if you use specialist equipment at your club you may need to increase the value of cover.
At Protectivity policies start at just £3.62 a month*.
Prices from
£3.62 a month*
Explainer quote
Policy cost
£3.62* a month
Policy type
Theatre Club Insurance
Policy duration
Annual
Public Liability
£1,000,000
Professional Indemnity
£1,000,000
Equipment Cover
£500
This example is based on a real quote from our website on 1/10/2024. If your circumstances and cover needs differ, your quote may be more or less expensive than the above example. The quote you receive will reflect the information you share about your event. The quoted price may vary from those displayed here.
Have a question?
For further information on your policy, renewals, making a claim and contacting us, you’ll find an extensive list of FAQs on our Help & Support page.
Why choose Protectivity for your theatre & performing arts insurance policy?
Let the reviews of over 3,500 customers explain why you should choose us.¹
Trusted by over 180,000 customers.
Experienced insurance providers for over 30 years.
Over 3,500 highly rated reviews.
Proof of our excellent customer service.

Experienced Claims Handling
A smooth and efficient claims process.

UK Based Customer Support
On average we answer your phone calls in under 2 minutes
Frequently
Asked Questions
Do I need Employers’ Liability for a sports club?
As a club owner or manager, you will need employers’ liability insurance if you are employing anybody, whether they are a paid member of staff or volunteers. Employers’ liability will protect you against any claims from your employees (including volunteers) who have been injured or become seriously ill as a result of working with you. Employers’ liability can be included in any sports club insurance policy with Protectivity.
What is Professional Indemnity for sports clubs?
Professional indemnity, or sometimes known as professional liability, will protect your sports club or association for any advice, tuition or instruction which has been given by a suitably qualified member of your staff.
Do I need Public Liability Insurance for a sports club?
All our club insurance policies include public liability as standard. This means that you will be protected from any third-party claims made against you, whether that is accidental injury to another person or damage to third party property, and/or claims made by any members of the club. All individuals who take part in sport and recreation have a duty of care to ensure they do not cause personal injury, financial loss, or damage to property. If their actions do cause injury, loss or damage and “negligence” can be proved, they become liable to pay for compensation as a result of their actions.
What type of clubs do you insure?
We can insure the following clubs: running clubs, football clubs, golf clubs, dance clubs, martial arts clubs, cricket clubs, ramblers clubs and associations, tennis clubs, fishing clubs and many more. If you have any questions regarding your club just give us a call on 01494 887909 and we’ll be happy to talk through your club’s needs with you.
Discover more from Protectivity
This page content has been created for pre-purchase information and should not be taken as advice.
*Prices quoted refer to a quote raised from our website 1/12/2025. Prices will differ depending on requirements. Make sure you have the correct level of cover for what you need. For the most accurate pricing, please get a quote and for full details on what is covered refer to our policy documentation with your quote.
** Based on Protectivity sales data from 2007 to present
¹Based on live Feefo data