How will Professional Indemnity protect a personal trainer?

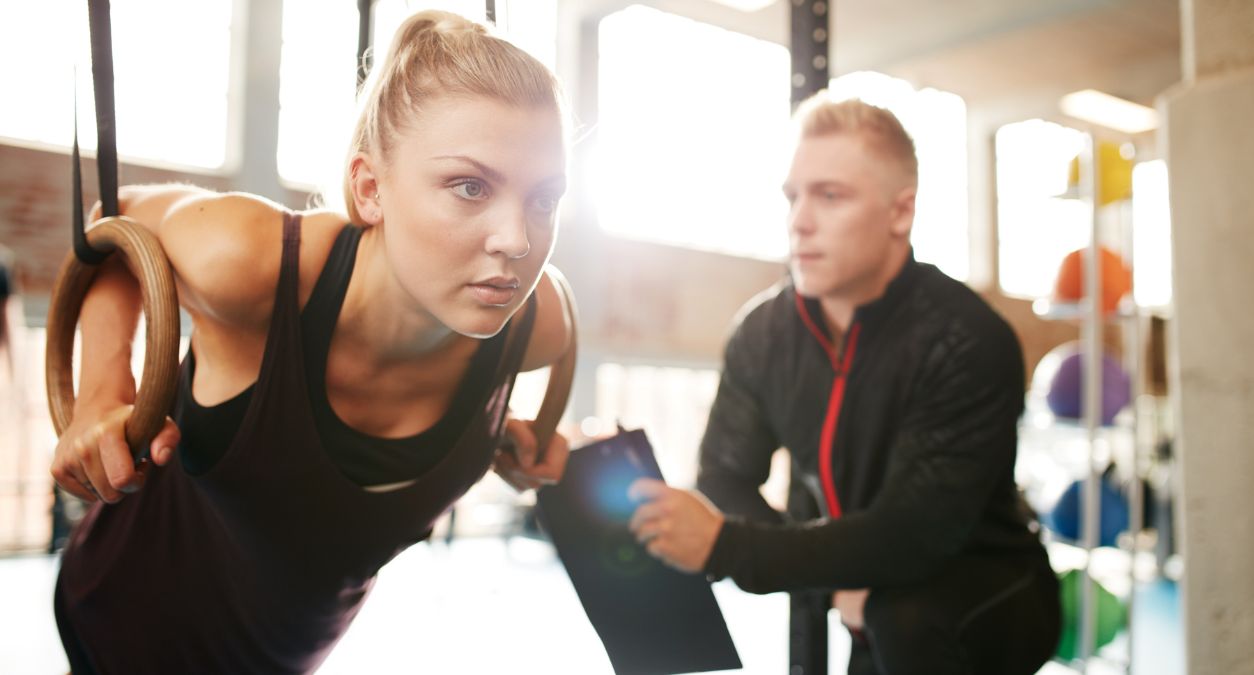
Fundamentally people hire a personal trainer to act as a professional advisor on their fitness regime. Through the drills and routines they set for their customers, the end goal, whether it be strength training or weight loss, can be attained.

However, it’s not always that straightforward. Injuries can occur and on rare occasions relationships between clients and customers can grow fractious.

For example, a client may feel that a particular personal training session has left them with an injury. If they believe that it was the fault of the trainer, they may go on to sue.

The trainer, on the other hand, may disagree. They may believe that any injury has come about because of the client’s failure to execute an exercise properly.

Whether the blame truly lies with the professional or not, they will still need to defend themselves if their client sues.

That is where Professional Indemnity comes into play.

The costs of defending such a claim can soon stack up. Furthermore, the financial implications can become even more severe should the court side with the client.

When a personal trainer takes out a policy with Protectivity Insurance, the level of Personal Liability cover (£1 million) is matched by our Professional Indemnity cover.

This means that legal costs are covered should a client claim negligence on the trainer’s part which results in injury. That includes any damages that may ensue should the court rule that the trainer was in fact to blame.

Professional Indemnity is just one of the benefits of ensuring you have comprehensive personal trainer insurance.

All of Protectivity’s policies come with the aforementioned Personal Liability and Indemnity match. But they also benefit from £250 equipment cover and Personal Accident cover, should they injure themselves during a session.

If you are a Personal Trainer and are looking for comprehensive Public Liability and Professional Indemnity insurance, then buy your personal trainer cover online now.
 

*Disclaimer – This blog has been created as general information and should not be taken as advice. Make sure you have the correct level of insurance for your requirements and always review policy documentation. Information is factually accurate at the time of publishing but may have become out of date. 

Recent Blogs

How to Start a Plumbing Business in the UK Image

Business

How to Start a Plumbing Business in the UK

Starting a plumbing business can give you greater freedom over the jobs you take on, your working hours and how y

Getting paid: Which payment system is right for your small business? Image

Business

Getting paid: Which payment system is right for your small business?

You have done the work, made the sale or delivered the service. Now you need to get paid.  For a small busine

How higher interest rates affect your small business Image

Business

How higher interest rates affect your small business

When you’re busy running a small business, the effects of interest rates aren’t always obvious. A finance quo

What can go wrong at a Christmas party? Common risks for event organisers Image

Business

What can go wrong at a Christmas party? Common risks for event organisers

Christmas parties are supposed to be about good food, music, drinks and spending time together – not worrying a

Saving for retirement as a sole trader Image

Business

Saving for retirement as a sole trader

Building more freedom for your future  When you work for yourself, there is always something that needs payin

How to improve cash flow as a tradesperson Image

Trades

How to improve cash flow as a tradesperson

Having plenty of work doesn't necessarily mean having plenty of money in the bank.  For tradespeople, there's

Hiring staff for your salon: What you need to know Image

Business

Hiring staff for your salon: What you need to know

There often comes a point when running a busy salon starts to feel different. Maybe your diary is consistently

Could your business survive losing your phone? Image

Business

Could your business survive losing your phone?

If you’re self-employed, there’s a good chance your phone does far more than make calls. It might hold you

Hourly rate vs day rate: which is best for contract work? Image

Business

Hourly rate vs day rate: which is best for contract work?

Working for yourself gives you more freedom over how you work, who you work with and what you charge. But sett

What changes when your side hustle becomes your main job Image

Business

What changes when your side hustle becomes your main job

Starting a side hustle can be an exciting way to earn some extra money, test a business idea or turn something yo

Simply find the insurance you need.